The Fundraising Funnel Is a Supply Chain Problem — And Cross-Border Sellers Already Know How to Fix It
Cross-border operators spend their lives solving one problem: getting the right product in front of the right buyer at the right moment, without burning margin on the wrong audience. We obsess over match quality — keyword-to-listing relevance on Amazon, creative-to-audience fit on TikTok Shop, catalog-to-buyer alignment on Etsy. So when a tool like Pitchfire shows up claiming to solve investor-founder matching with AI, my instinct isn’t “cool, another fundraising app.” It’s “this is the same matching problem we solve every day, applied to a different inventory.” And the way Ryan O’Hara and team have framed it — portfolio fit, thesis alignment, prior reaction signals — reads like a relevance-scoring model I’d recognize from any mature marketplace. That’s why it’s worth a look, even if you never raise a dollar.
What Pitchfire Actually Solves (And Why the Analogy Isn’t a Stretch)
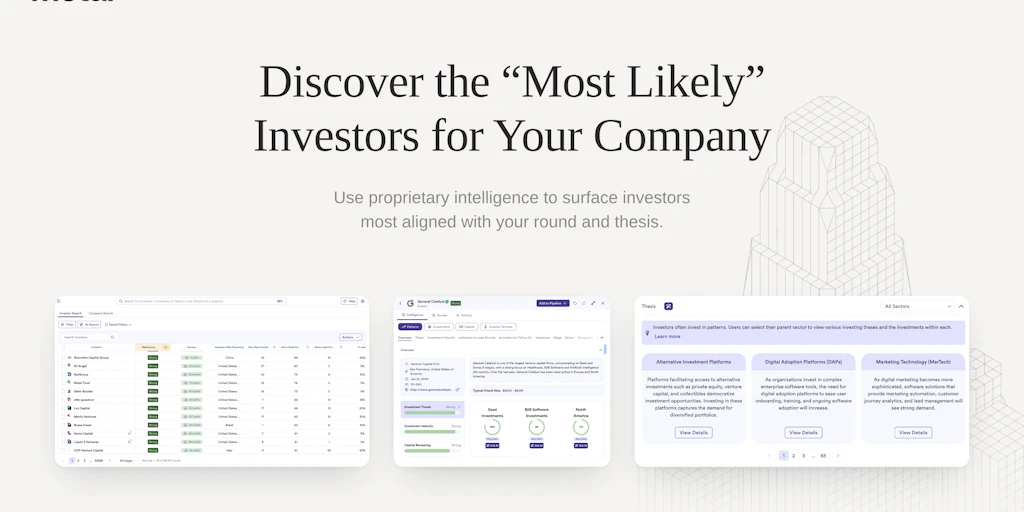
The pitch, per O’Hara’s launch comment, is straightforward: when he was raising for his previous startup, “it was so hard to find VCs that were actually a good fit, and so much work to get an introduction to them.” The result was a giant spreadsheet — his words — and a cold-email grind that mostly went nowhere, a pain echoed by Robin de Lacroix in the comments.
That is the exact failure mode of a bad product-research workflow. You build a spreadsheet of 400 “potential winners,” you spray outreach, you get a 1% reply rate, and you conclude the channel is dead. It isn’t the channel — it’s the targeting. Pitchfire’s answer, per O’Hara, is to score investors on “their existing portfolio, criteria on the website, thesis, and reactions to previous startups we’ve sent to them.” That last signal is the interesting one. It’s behavioral, not declarative. A VC’s stated thesis is like a seller’s stated category on a wholesale platform — often aspirational, sometimes stale, and rarely the whole truth. What they actually funded is the ground truth.
Why Amazon sellers should care more than Shopify ones
If you run a Shopify DTC brand with a clean P&L and no inventory debt, you can grow on cash flow and never touch venture money. If you run an Amazon FBA operation — especially one carrying Seller Central inventory across multiple marketplaces, dealing with FBA fee changes, and fighting for Helium 10 keyword real estate — your capital needs are lumpier and your cash conversion cycle is brutal. That’s the profile that ends up pitching. And it’s the profile most likely to waste three months on the wrong 40 investors.
How It Differs From the Existing Options
The fundraising tooling space isn’t empty. You’ve got the CRM-style approach — Airtable or Notion databases that founders manually curate, which is what O’Hara was doing. You’ve got data-layer players that index funding rounds and firm portfolios. And you’ve got the cold-outreach infrastructure — Apollo, Instantly, various email sequencers — that automate the sending without improving the matching. Pitchfire’s bet is that the matching layer is the bottleneck, not the sending layer.
That’s a defensible thesis, and it mirrors a shift we’ve already lived through in e-commerce. For years, the growth conversation was about volume — more emails, more ads, more SKUs. Then Klaviyo and the CDP wave taught us that segmentation beats volume. Then Meta Advantage+ taught us that algorithmic match beats manual targeting. Pitchfire is essentially applying the “let the model find the fit” logic to a domain that’s still running on spreadsheets and cold DMs.
Where the math breaks
Here’s my skepticism, and it’s the same skepticism I’d apply to any two-sided matching product. The value of a match is only as good as the supply on the other side. If 50,000 founders are all being matched to the same 300 relevant VCs, you haven’t solved the funnel — you’ve just added a smarter queue to a clogged inbox. Gal Dayan raised exactly this in the comments: “VCs already get flooded with cold decks, so what stops this from becoming just another inbox they learn to ignore?”
O’Hara’s answer is the two-sided screen: when VCs use Pitchfire on their side, “our AI associates for them will automatically screen those applicants away.” That’s the right architecture — it’s a marketplace with demand-side filtering, not a one-way outreach cannon. But it only works if enough investors adopt the investor-side product. Until then, you’re back to the cold-email grind with better targeting. Which is still an improvement, just not a revolution.
What Cross-Border Sellers Can Borrow From This
Strip away the fundraising context and Pitchfire is a case study in three operator-relevant patterns.
First: use behavioral signals over stated preferences. O’Hara explicitly weights “reactions to previous startups we’ve sent to them” alongside stated thesis. In e-commerce terms, that’s the difference between targeting a customer by the interests they claim in a survey and targeting them by the products they actually bought. If you’re building lookalike audiences on Meta, you should be feeding the pixel from purchasers, not from page-viewers or add-to-carters. If you’re doing TikTok Shop creator outreach, weight creators by past conversion on similar SKUs, not by their follower count or stated niche.
Second: two-sided filtering beats one-sided spray. The cleanest version of this in our world is Amazon Sponsored Brands vs. Sponsored Products — the former lets you filter by shopper intent signals (brand queries, category browse), the latter is closer to a blunt keyword match. The Pitchfire insight is that the receiving side should have its own filter, not just the sending side. If you’re running influencer campaigns, build a rejection layer on the creator side: auto-decline anyone whose audience geography or engagement pattern doesn’t match your target market. That’s a two-sided screen.
Third: the spreadsheet is a symptom, not a tool. O’Hara’s “big spreadsheet” complaint is universal. Every operator I know has a “master sheet” somewhere that’s slowly rotting. The lesson isn’t “buy software” — it’s “if your workflow requires a human to manually maintain a list of 400 rows, the workflow is broken.” That applies to supplier lists, creator lists, wholesale outreach lists, and yes, investor lists.
A sidebar for DTC operators considering a raise
If you’re a Shopify brand doing $2M–$10M and thinking about raising, the Pitchfire framing is useful even if you never use the product. Write down your investor thesis as if you were the VC: what portfolio companies would look like yours, what stage, what check size, what geography. Then cross-reference against actual funded companies in the last 18 months. The gap between “who says they fund DTC” and “who actually wrote checks to DTC brands in the last two quarters” is where your real target list lives. That’s a two-hour exercise with Crunchbase and a spreadsheet, and it will save you months.
Where My Judgment Says It Falls Short
Three honest concerns.
The cold-start problem is real. Two-sided marketplaces are brutal to bootstrap. If Pitchfire launches with strong founder supply but thin investor supply, the matching quality degrades fast, and founders churn. O’Hara mentions “solo GPs and smaller funders ready to write checks but don’t have the marketing brand to drive inbound” as a beachhead — that’s smart, because those investors have the most to gain from a matching layer. But it’s a narrow segment, and the big-name firms that founders actually want are the hardest to onboard.
“AI matching” is doing a lot of work in that pitch. O’Hara’s description of the matching logic — portfolio, criteria, thesis, reactions — is essentially a structured relevance score. That’s fine. But the phrase “AI associates” implies a level of autonomous screening that, in practice, usually means “a rules engine with an LLM wrapper.” I’d want to see how the system handles edge cases: a founder pivoting categories, a VC whose thesis just changed, a portfolio company that quietly died. Matching models are only as good as their freshness.
The outcome metric is meetings, not checks. O’Hara says he’s “excited to help founders get some meetings.” Meetings are a leading indicator, not the KPI. The real question is whether Pitchfire-matched intros convert to term sheets at a higher rate than cold outreach. That data won’t exist for months, and until it does, the product is a productivity tool, not a proven edge.
What I’d Watch / Test Next
If you’re an operator with a raise on the horizon, do three things this week. First, audit your current investor list against actual recent checks — not stated thesis — using Crunchbase or PitchBook, and cut anything that hasn’t funded in your category in 18 months. Second, build a two-sided filter for your own outreach: a short pre-qualification form or a set of auto-decline criteria that protects the recipient’s inbox, whether that’s an investor or a wholesale buyer. Third, watch whether Pitchfire publishes any conversion data — reply rates, meeting-to-term-sheet rates — over the next two quarters. If they do, it’s a signal the team is serious about outcomes, not just introductions. If they don’t, treat the tool as a smarter spreadsheet and nothing more. The matching problem is real. The solution is still unproven.