The $1,299 Question Every Cross-Border Seller Should Be Asking About the New Meta VR Glasses
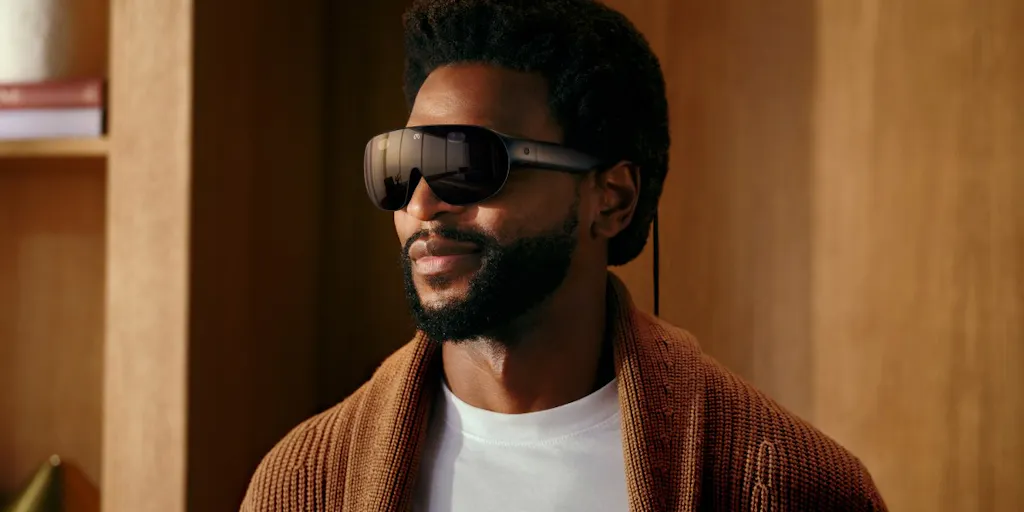
Meta just made its biggest VR hardware bet in years, and it has almost nothing to do with VR. The new Meta VR Glasses weigh around 100g because the compute and battery got shoved into a pocket puck — roughly 5x lighter than a Quest 3 — and they ship next spring at $1,299.99. For a cross-border operator, the headline isn’t the spec sheet. It’s that Meta is asking a $1,300 question about where the next hardware accessory category gets manufactured, fulfilled, and taxed. If you sell anything that touches a headset — straps, cases, prescription inserts, charging docks, travel pouches — this launch is a product-research signal, not a gadget review.
What Problem the Glasses Actually Solve (and Why the Puck Is the Whole Story)
Strip away the marketing and the engineering decision here is a thermal and ergonomic one. Face-mounted compute is heavy, hot, and battery-constrained. Meta’s answer — confirmed in the launch thread — is to move the heavy, hot, power-hungry parts off your head and into a tethered puck. The face unit gets eye and hand controls, VR apps and games, 3D movies, immersive sports, a multi-screen workspace, and Meta AI built in. The puck does the sweating.
That architecture matters commercially for one reason: the accessory surface area just doubled. A tethered puck means cables, clips, belt holsters, pocket liners, replacement tethers, and a brand-new failure point that third-party sellers can exploit. Every prior headset generation spawned a cottage industry of comfort mods because the stock experience was uncomfortable. Meta has pre-solved the comfort problem on the head — which sounds like bad news for accessory sellers, but it’s actually the opposite. When the core device gets good, buyers stop modding for survival and start modding for convenience and identity. That’s a higher-margin, less price-sensitive purchase.
Why Amazon sellers should care more than Shopify ones
If you run an Amazon FBA brand, this is a familiar pattern. A major platform drops a hero SKU with a fixed launch window (“next spring”), a known price point ($1,299.99), and a rabid early-adopter base that will buy accessories before the device even ships. That’s a keyword-arbitrage window. Search volume for “Meta VR Glasses case,” “puck holster,” “100g headset strap” will spike months before inventory lands, and the sellers who register Brand Registry and lock listings early capture the organic rank that latecomers pay Amazon Ads to rent.
DTC operators on Shopify face a harder math. You can build a beautiful bundle page, but you’re fighting for cold traffic against Amazon’s default-search gravity on a category buyers don’t yet know exists. My honest read: the accessory play here is an Amazon-first, DTC-second motion — own the search term, then use the packaging insert to migrate buyers to a subscription or a higher-margin bundle.
How This Differs From the Incumbents You Already Sell Against
Meta isn’t launching into a vacuum. The comparison set matters because it tells you where the price umbrella sits.
- Against the Quest 3: This is the same company cannibalizing its own line. The Quest 3 is a self-contained headset; the new glasses offload compute. For sellers, that means the Quest accessory ecosystem doesn’t transfer cleanly — different weight class, different mounting, different power topology.
- Against Apple Vision Pro: Apple went the opposite direction — heavy, premium, all-in-one, $3,499 at launch. Meta at $1,299.99 is positioning as the accessible tier. That price gap is where third-party margin lives.
- Against the broader AR/VR field (Ray-Ban Meta, Xreal, Rokid): The puck design is a hybrid — it’s not a true standalone AR glasses play and not a full VR rig. That ambiguity is exactly why the accessory market is undefined and therefore open.
Where the math breaks
Here’s the uncomfortable part. A $1,299.99 device is not a mass-market impulse buy. The addressable buyer pool is smaller and more affluent than the Quest 3 crowd, which means your accessory TAM is narrower than the raw “VR is growing” narrative suggests. If you’re modeling units, don’t extrapolate from Quest attachment rates. Model from premium-electronics attachment rates — think DJI drone accessories or high-end camera gear, where buyers spend real money but in smaller volumes. The winner in this category won’t be the seller with the cheapest case. It’ll be the seller who reads the puck as a lifestyle object and prices accordingly.
What Cross-Border Sellers Can Actually Borrow From This Launch
Three transferable lessons, independent of whether you ever touch VR.
1. The “offload the heavy part” pattern is a product-research heuristic. Meta moved compute off the face. Apply the same lens to your own category: what’s the heaviest, hottest, most failure-prone component of the thing you sell, and can it be separated? That’s how you find the next accessory SKU — by finding the part the OEM left exposed.
2. Launch windows are inventory-timing signals. “Next spring” plus a fixed price is a gift. It gives you a countdown to source, list, and rank. Most sellers treat hardware launches as news; operators treat them as a demand-forecasting input for keyword and ad planning.
3. Community threads are underrated demand research. The Product Hunt comments on this launch are thin but telling — one buyer calls himself a “day one buyer,” another fixates on the 100g figure. That’s raw signal about which spec drives purchase intent. Scrape that language and put it in your listing bullets.
Why the 100g number is the real marketing hook
Notice what the commenters latched onto: not the apps, not Meta AI — the weight. “Wow 100 grams?” That’s the number that sells. If you’re building accessory listings, lead with weight and comfort, not compatibility checklists. Buyers already know what it does. They’re buying relief from what it was.
Where My Judgment Says This Falls Short
I’ll be blunt about the gaps, because the source material doesn’t answer them and neither does Meta’s launch framing.
- No disclosed accessory roadmap. Meta has historically been hostile to third-party mods in some categories and permissive in others. Whether it opens a licensed-accessory program — the way Apple’s MFi works — is not disclosed. That single decision determines whether this is a gold rush or a locked garden.
- The puck introduces a new failure point with no warranty clarity. A tethered compute puck means cable wear, connector fatigue, and pocket-heat issues. For sellers, that’s opportunity (replacement parts) and risk (returns, A-to-z claims). The source says nothing about durability specs.
- $1,299.99 is a demand ceiling, not a floor. I think the accessory TAM is real but smaller than the hype implies. Anyone modeling this as “the next AirPods case market” is going to over-order.
- Timing risk is underrated. “Next spring” is a soft window. Hardware slips. If you commit inventory to a launch that moves two quarters, you’re carrying dead stock through a Q4 you didn’t plan for.
The honest verdict: this is a watch-and-prep signal, not a buy-inventory-today signal. The sellers who win will be the ones who build the keyword and listing infrastructure now and place small test orders close to the confirmed ship date — not the ones who go all-in on a press release.
What I’d Watch / Test Next
Concrete moves for this week, no fluff.
- Set a keyword watchlist. Pull search volume for “Meta VR Glasses,” “puck holster,” “100g headset,” and “VR glasses case” in Helium 10 or Jungle Scout. Track the trend weekly. You’re looking for the inflection point, not the peak.
- Register the brand and the listing early. Secure Amazon Brand Registry for any accessory brand name you plan to use, and draft listings now so you can publish the day the device ships.
- Source small, test the puck form factor. Order samples of pocket-puck holsters and tether replacements from your existing suppliers. Don’t commit to MOQs until Meta confirms the ship date.
- Watch for a licensing program. If Meta opens an official accessory certification, that changes the entire risk profile. Set a Google Alert for “Meta VR Glasses accessory program.”
- Model conservatively. Use premium-electronics attachment rates, not VR-mass-market ones. If the numbers don’t work at half your optimistic unit forecast, they don’t work.
The puck is the product. The accessory market is the opportunity. But the window is a countdown, not an open door — and the sellers who treat it that way will be the ones still standing when the device actually ships.